Business Banking at California Credit Union: Commercial Lending in Southern California
Last updated on October 14, 2026
Discover how California Credit Union helps businesses of all sizes across Southern California grow through flexible financing, relationship-first service and the “People Helping People” philosophy.
- SBA Preferred Lender offering faster, more flexible small business financing
- Commercial real estate financing for owner-occupied and investment properties
- Equipment, expansion and working capital financing tailored to each stage of growth
- Dedicated relationship managers who understand cash flow, business operations and the story behind the numbers
- Member-owned, community-focused banking that reinvests in the local economy
Learn how our Business Banking team supports businesses of all sizes throughout Southern California.
California Credit Union has helped businesses of all sizes meet their banking needs for decades. As an SBA Preferred Lender offering competitive rates, backed by a skilled team with years of combined experience across Southern California, we've worked with businesses in every industry to create flexible financing solutions.
Over time, our Business Banking team has become a valued, trusted partner to countless local businesses. Many of these relationships span decades and every stage of a business's lifespan, from initial funding capital and startup to growth and expansion. And because credit unions like California and North Island Credit Union are member-owned institutions that live by the "People Helping People" philosophy and prioritize community development, we build personal relationships with local businesses that go beyond spreadsheets and numbers, and we can often offer more flexible solutions when you need to grow or adapt.
Leading our Business Banking team is Brandon Jensen, Vice President of Business Banking and Commercial Lending. We sat down with Brandon to learn more about business banking at credit unions, how the team supports businesses of all sizes throughout their lifespan, why relationships matter and what keeps business members choosing to stay and grow with California Credit Union.
California Credit Union: As Vice President of Business Banking and Commercial Lending, you work closely with businesses at all stages of growth and often build relationships that last for years. From your perspective, what keeps business members choosing to stay and grow with California Credit Union over time? And how do those long-term relationships make an impact on the communities we serve?
Brandon: I think it really comes down to relationships, trust and consistency. Business owners want to work with people who understand their business, know their history and are invested in where they’re trying to go. As those businesses grow, their financial needs often become more complex. What may begin as a deposit relationship, or a smaller credit need, can grow into commercial real estate financing, equipment or expansion financing, treasury management and a much broader banking relationship.
Our goal is to grow alongside our members and be a consistent resource throughout that journey. The longer we work together, the better we understand their business, their goals and the challenges they face, which allows us to provide more thoughtful solutions.
One of the things I enjoy most about business banking is that you get to see how helping one member can have a much broader impact. When we help a local business succeed, that business creates jobs, supports other local businesses and vendors, provides important services and reinvests in the community.
California Credit Union: What does the “People Helping People” philosophy look like to you in the business banking world, and how does your team bring that to life in your day-to-day work with members?
Brandon: To me, “People Helping People” doesn’t stop when somebody becomes a business owner. Behind every business is a person or group of people who took a risk, had an idea and are trying to build something. They also have employees, families, customers and communities that depend on their success.
For our team, helping doesn’t always mean simply making a loan. Sometimes it means finding a better way to structure a transaction, identifying a challenge early, connecting a member with another resource or helping them think through whether taking on additional debt is the right decision at that moment.
We want our relationship managers to understand the entire picture and use their expertise to help members make good financial decisions. I also believe responsible underwriting is an important part of “People Helping People.” Our responsibility is to help members grow in a way that is sustainable while also protecting the cooperative and the members whose deposits ultimately allow us to lend.
California Credit Union: A lot of businesses today want more than just a lender, they’re looking for someone who really understands their goals and challenges. How does your team show up in that way, and how is that experience different from working with a larger, traditional bank?
Brandon: I think one of the biggest differences our members feel is access. We want our members to have a banker they can actually call, someone who already knows their business, understands what they’re trying to accomplish and can help them navigate the organization.
Our relationship managers aren’t simply there to take an application or sell a product. They’re expected to understand cash flow, business operations, commercial real estate, financing structures and treasury management, then bring the right resources together based on what that particular member needs.
I like to think of it as bringing the sophistication and capabilities of commercial banking together with the relationship experience people expect from a credit union. As a business becomes more complex, having somebody who understands both the numbers and the story behind those numbers becomes increasingly valuable.
California Credit Union: California Credit Union works with a wide range of businesses, from small, family-run shops to larger, more complex organizations. How do you tailor your approach to meet such different needs, and what does that say about the role we play in the broader business community
Brandon: The size and complexity of the business may change, but our process really starts in the same place: listen first.
A small business owner may be purchasing their first commercial property and need someone who can walk them through that process. Another member may own multiple businesses or properties and have complex cash flow, financing and treasury management needs. The sophistication of the solution changes, but the level of attention shouldn’t.
That means taking the time to understand where the member is today and where they want to go, then tailoring the relationship around those needs, whether that involves commercial real estate financing, an SBA solution, equipment or working capital financing, or treasury and deposit services. We can meet businesses where they are today while having the expertise and capabilities to continue serving them as they grow and become more sophisticated.
California Credit Union: You’ve worked with a lot of businesses over time, are there any specific stories or partnerships that stand out to you and really show the value of taking a relationship-first approach?
Brandon: There are quite a few, but one that stands out involves a small, closely held restaurant that has been part of its East County community in San Diego for many years.
Our relationship with the owners began when they purchased the business. We supported them with the deposit services they needed to operate and, as the restaurant grew and established itself, eventually provided a line of credit to support the business. Over the course of roughly a decade, we had the opportunity to be part of both their business and personal financial journeys, which gave us a deep understanding of their operation and what they had built in the community.
Years later, an opportunity came along for them to purchase the building where they had been operating the restaurant. The property also included several smaller tenant spaces, creating an opportunity for them not only to become owners of the real estate their business occupied, but also to generate additional rental income. For a modest, family owned business, however, the required down payment could have put that opportunity out of reach.
Because we knew the members, understood their business and understood the story behind the numbers, our team was able to work closely with them to find a solution. The restaurant occupied enough of the property to qualify for SBA owner occupied financing, which significantly reduced the required down payment and ultimately made the purchase possible.
That transaction changed the economics of their business. It reduced their monthly occupancy expense, created an additional source of income and gave them the freedom to make decisions about a property they had spent years operating in as tenants. Most importantly, they became owners of an asset that could continue building value for their family.
For me, that relationship represents what business banking at a credit union can be at its best. We didn’t simply finance a real estate transaction. We had the privilege of watching members purchase a business, helping support them as they grew it, then working alongside them nearly a decade later as they achieved the dream of owning the property where they had built that business. That’s the kind of full life cycle relationship that makes this work incredibly rewarding.
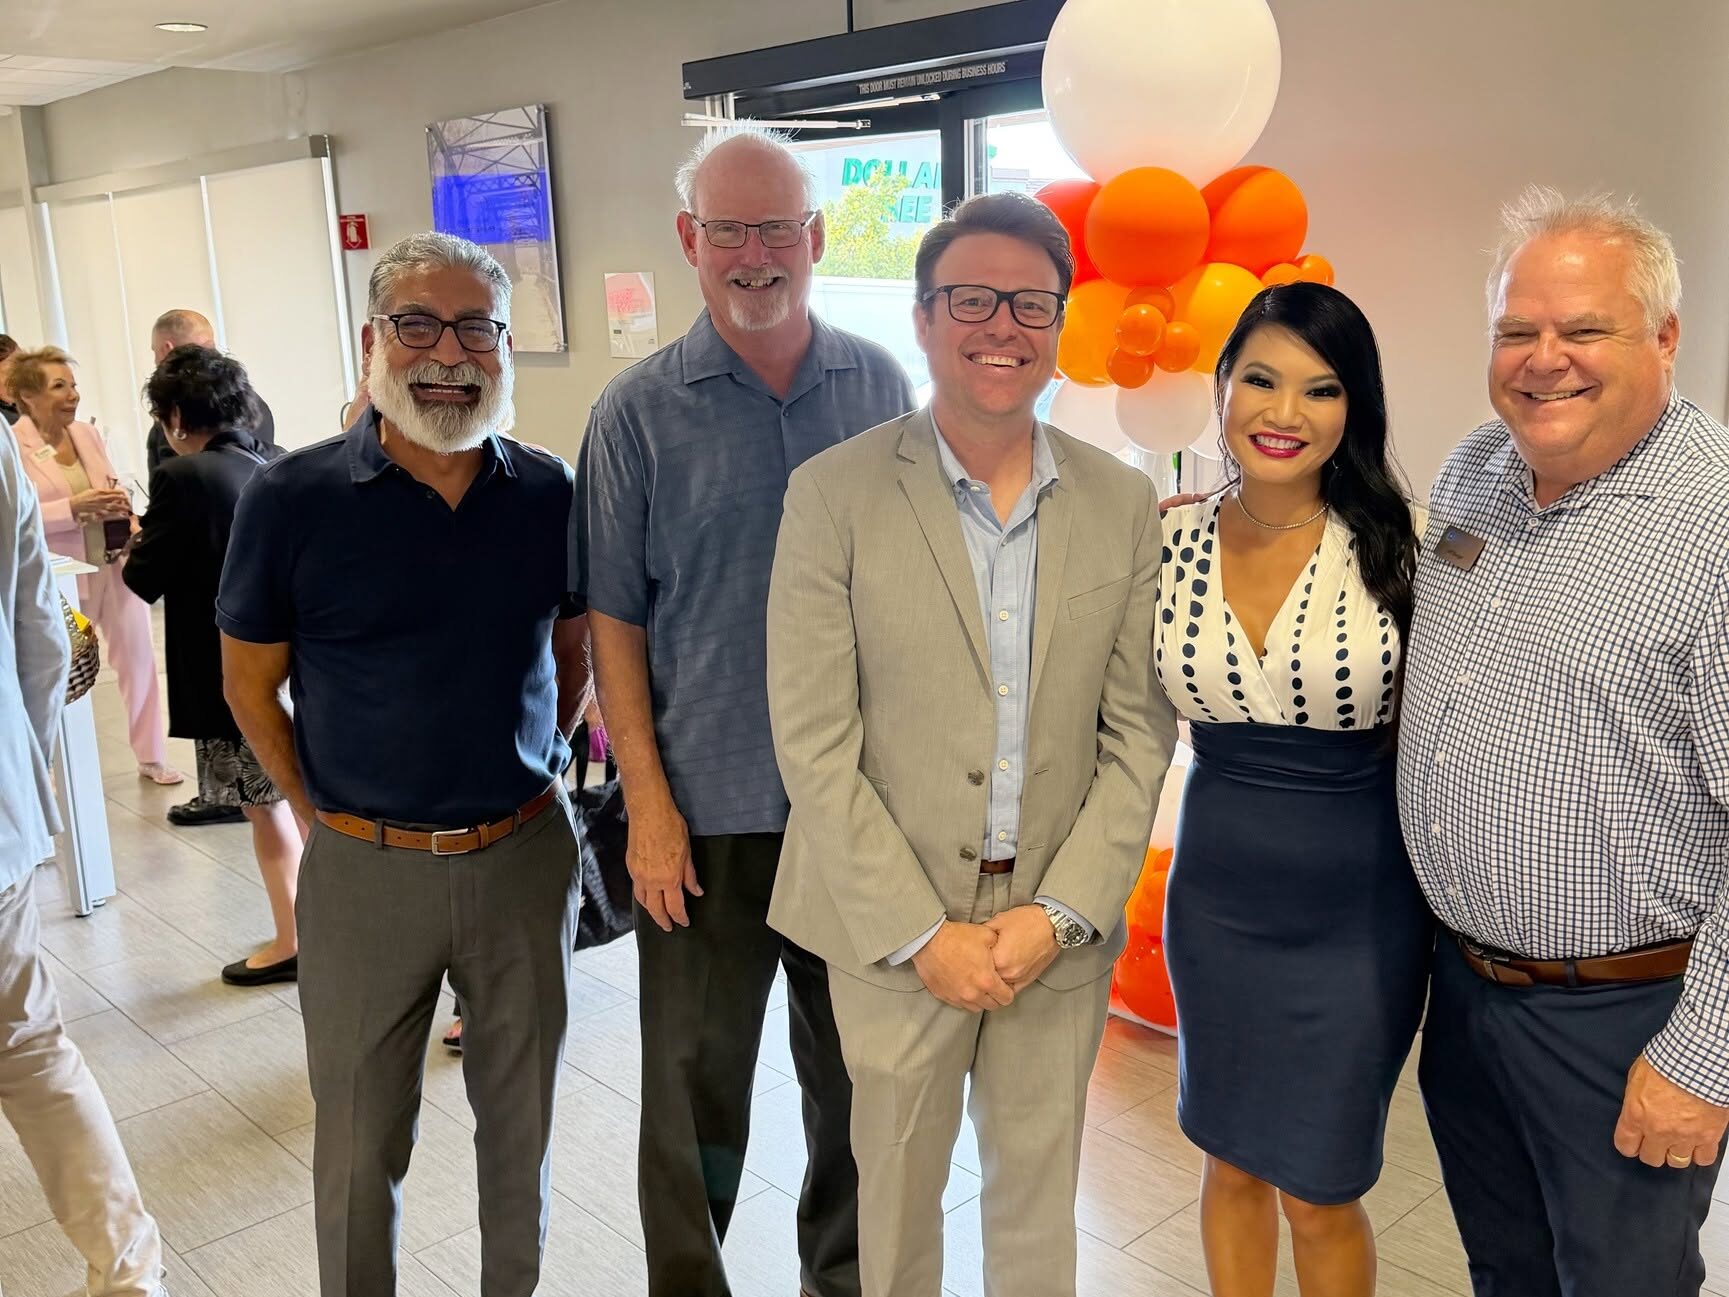
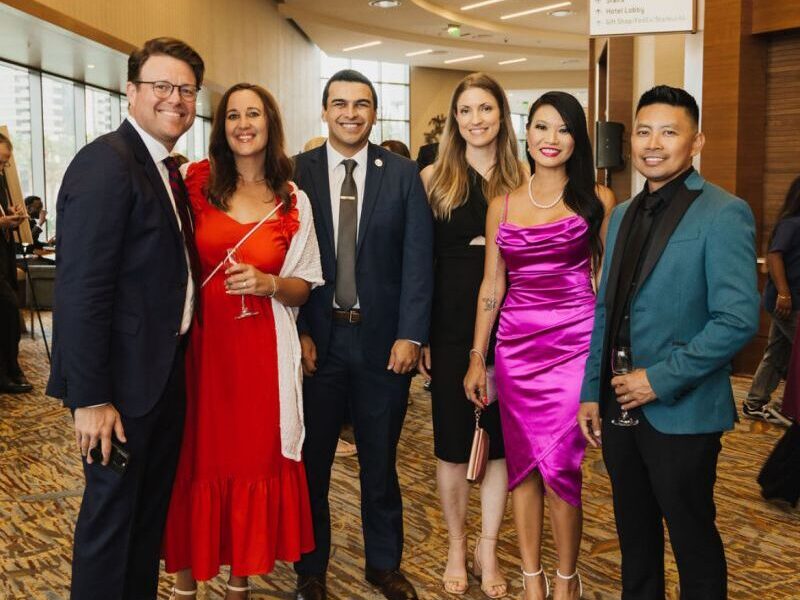
California Credit Union: Over the summer, you helped host a California Credit Union League (CCUL) mixer, bringing together fellow CCUL members from across the region for an evening of networking and industry connection (click here to see more of this event). As both a lender and a credit union member, how important is it to build and strengthen these relationships with our fellow credit unions?
Brandon: One of the things I love most about the credit union movement is that collaboration really is part of our DNA. We may compete in the marketplace, but there is also a genuine willingness among credit unions to share ideas, develop relationships, learn from one another and work together to make the entire movement stronger.
My involvement with California’s Credit Unions has given me the opportunity to see that firsthand. Bringing credit union professionals together locally helps us build relationships and share knowledge, but it also connects us to something bigger. When credit unions come together, we have a stronger collective voice on legislative and regulatory issues that affect our ability to serve members. Those relationships can also create opportunities to share expertise and resources across the movement. Ultimately, stronger credit unions mean more opportunities to serve members and communities, and I think maintaining that spirit of collaboration is incredibly important to our future.
California Credit Union: As things continue to evolve for local businesses, what are some of the biggest challenges you’re seeing right now? And how is California Credit Union helping business members navigate those changes and keep moving forward?
Brandon: I think uncertainty is probably the common thread we hear most often from business owners. The cost of capital has changed significantly over the last several years, while businesses are also managing higher costs for things like labor, insurance, real estate and other operating expenses. At the same time, business owners still want to grow, purchase property, hire employees and invest in their companies.
Our role isn’t to predict the future for them. It’s to understand their business, help them evaluate their options and provide responsible financial solutions that give them the ability to keep moving forward. Sometimes that means looking carefully at how a financing request is structured. Other times it means helping a member think about liquidity, cash management or how their banking relationship can operate more efficiently.
What continues to encourage me is the resilience of the business owners we work with. Even in an uncertain environment, we continue to see entrepreneurs investing in their companies and their communities. Our job is to be a trusted financial partner who can help them navigate those changes and help them take advantage of the right opportunities when they arise.